On Friday, 9 October 2026, the Prime Minister and Finance Minister, YAB Dato’ Seri Anwar Ibrahim, tabled Budget 2027. It is the second budget under the 13th Malaysia Plan and the fifth under the current government.
The Budget contains a great many proposals. Some are relevant to only certain industries and businesses but below are the 10 items that I found interesting which may be relevant to many businesses, in no particular order. Please note that the proposals remain policy items until the Finance Bill and the related Acts and subsidiary legislation (including exemption and remission orders, regulations and gazette notifications) are passed and gazetted. Details may therefore change.
At a Glance
| Item | Who is affected | In brief |
|---|---|---|
| 1. Minimum wage uplift | Employers (MSMEs exempted) | RM1,700 to RM2,000; income framework reform for semi-skilled beginning at RM2,500 |
| 2. Wages payment through banks and employer PTPTN repayments | Employers other than MSMEs | Deduction only where wages are paid through a bank account |
| Employers | New tax deduction | |
| 3. Spouses of Category I EP holders | Expatriate families and employers | Dependant Pass spouses may work |
| 4. BAKAT MADANI training | Participating companies | New tax deduction |
| 5. MSME income tax rates | MSMEs | One percentage point lower tax on the first RM600,000 |
| 6. Global Services Hub | GSH and Principal Hub companies | 5% rate, longer period, treasury exemptions |
| 7. Green Investment Tax Allowance | Green technology investors | Revised coverage |
| 8. Foreign currency loans | Borrowers from Malaysian banks | Stamp duty capped at RM2,000 or RM5,000 |
| 9. Malaysian shipping companies and Malaysian ship loans | Shipping companies | Full income tax exemption |
| Ship buyers and builders | Duty fixed at RM2,000 or RM5,000 | |
| 10. Multi-Family Office model | Families and licensed fund managers | New model beside the Single Family Office scheme |
The Ten Items
-
- Minimum wage uplift (and MSME carve-out) and reform in respect of the semi-skilled
The national minimum wage is to rise from RM1,700 to RM2,000 from June 2027, expected to benefit more than four million workers. MSMEs below the RM50 million annual sales threshold are stated to be exempted, to allow them time to adjust. The Government will also reform the workers’ income framework, beginning with a minimum wage of RM2,500 a month for semi-skilled workers and graduates. - Tax deduction on wages paid through bank accounts and for employer PTPTN repayments
To curb the employment of undocumented foreign workers, companies other than MSMEs may claim a tax deduction on wage expenditure only where wages are paid through a bank account, as permitted under the Employment Act 1955. The Budget text refers to both MSMEs and SMEs as exceptions, so we will watch the final legislative wording closely.
Additionally, employers who make PTPTN loan repayments on behalf of their employees will be entitled to a tax deduction for repayments made from 1 January 2027 to 31 December 2028. - Spouses of Category I Employment Pass holders allowed to work
From 1 January 2027, spouses of expatriates holding a Category I Employment Pass, who themselves hold a Dependant Pass, will be allowed to work in Malaysia, subject to conditions. - Tax deduction for BAKAT MADANI training
BAKAT MADANI was launched through commitments from six GLICs, PETRONAS and GLCs. To encourage private-sector participation, companies that provide BAKAT MADANI training programmes will receive a tax deduction for the period 29 June 2026 to 31 December 2030. - Reduction of the MSME income tax rate by one percentage point
Companies with paid-up ordinary share capital of RM2.5 million or below, and LLPs with partnership capital contributions of RM2.5 million or below, with annual sales not exceeding RM50 million, are categorised as MSMEs. They will enjoy a one percentage point reduction in income tax on the first RM600,000 of chargeable income.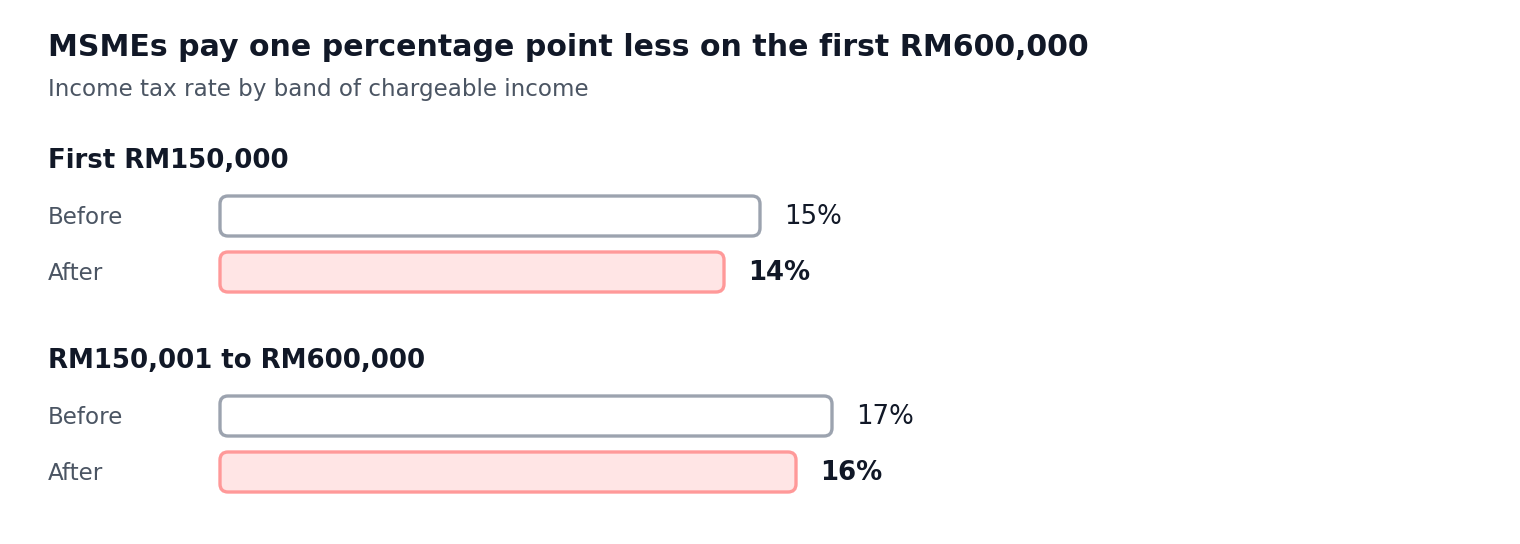
- Review of tax incentives for the Global Services Hub (GSH)
The GSH incentive has been reviewed and expanded. New companies will be offered a 5% rate, while existing GHSs and Principal Hubs will be treated differently according to their base income.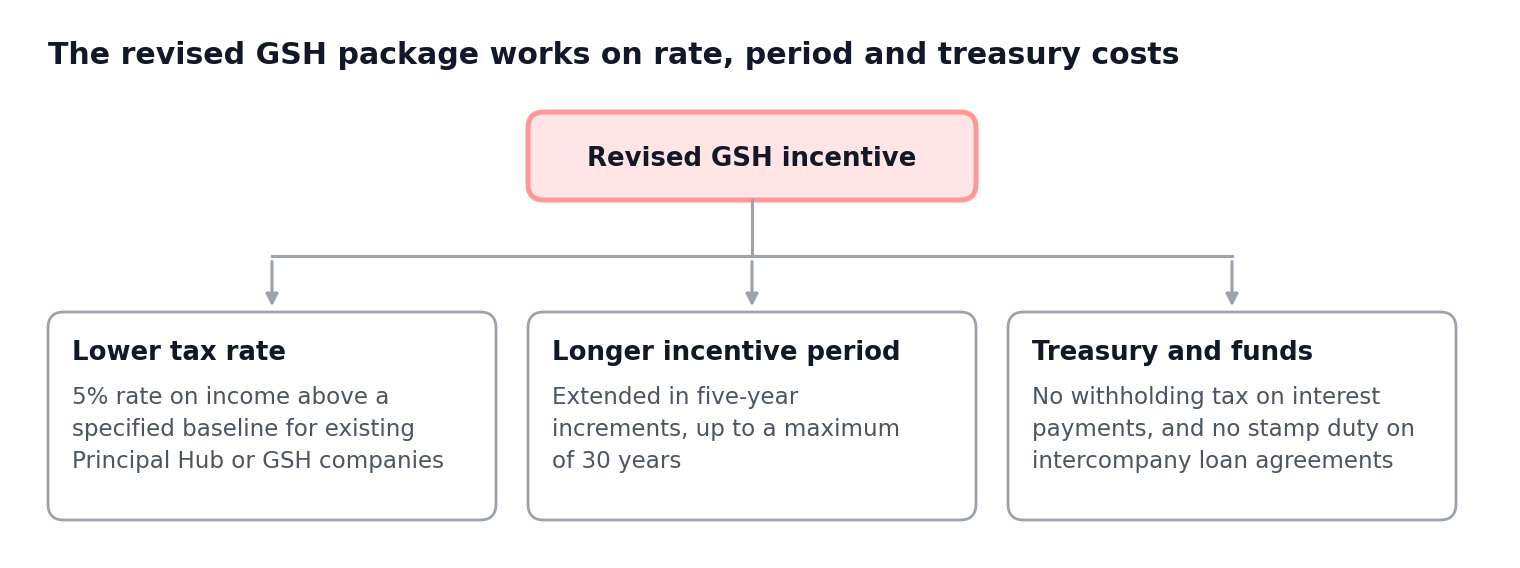
- Review of the Green Investment Tax Allowance (GITA)
Coverage has been revised for applications and assets from 1 January 2027 to 31 December 2030. It now includes green hydrogen and ocean thermal energy conversion, as well as specified locally produced green assets and storage systems. - Stamp duty on foreign currency loan and financing agreements
Foreign currency loan and financing agreements are currently subject to ad valorem stamp duty at 0.5%. For agreements with Malaysian banks executed from 1 January 2027, duty will be capped at RM2,000 for financing up to RM100 million, and RM5,000 above RM100 million.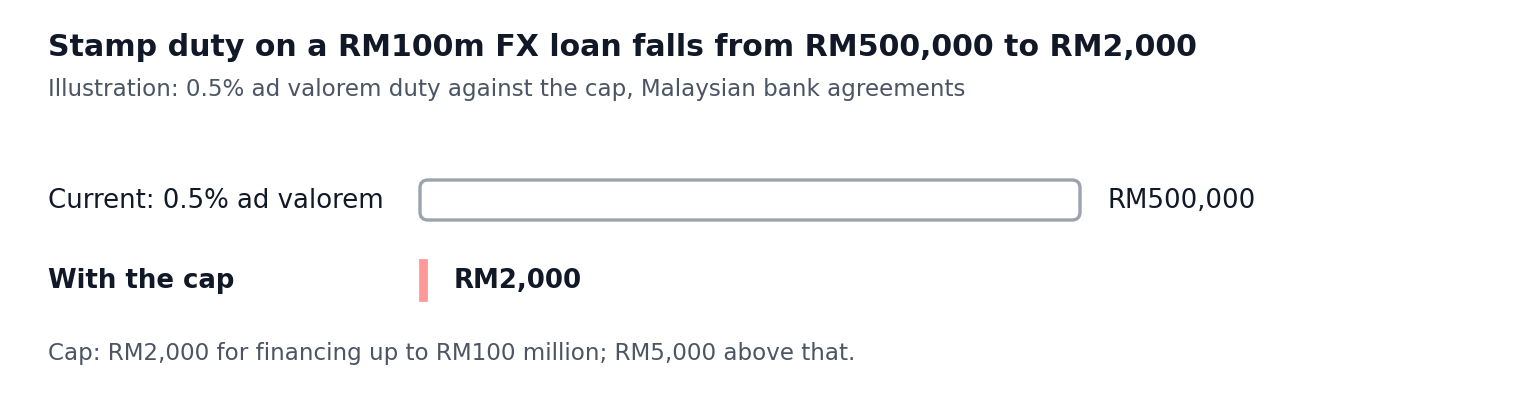
- Extension of tax exemption for Malaysian shipping companies and capping of stamp duty on loans for Malaysian ships
A full income tax exemption is proposed for YA 2027 to YA 2036, subject to strategic management and effective control in Malaysia, minimum Malaysian operating expenditure per ship, and minimum Malaysian employees and salary levels per ship.
Also, stamp duty on loans to purchase or build Malaysian ships will be fixed at RM2,000 for loans up to RM100 million, and RM5,000 for loans above RM100 million. - Introduction of a Multi-Family Office (MFO) model
The existing Single Family Office scheme in Forest City allows one family to manage its funds in Malaysia, with zero tax on qualifying income for up to 20 years. A Multi-Family Office model will be introduced, allowing licensed fund managers to serve several families, including approved SFO funds.
- Minimum wage uplift (and MSME carve-out) and reform in respect of the semi-skilled
This update is for general information only and does not constitute legal advice. Please seek specific advice before acting on any matter discussed.